Buying a used bike: smart ways to save on transit and avoid scams
A practical guide to shopping smart and avoiding theft.
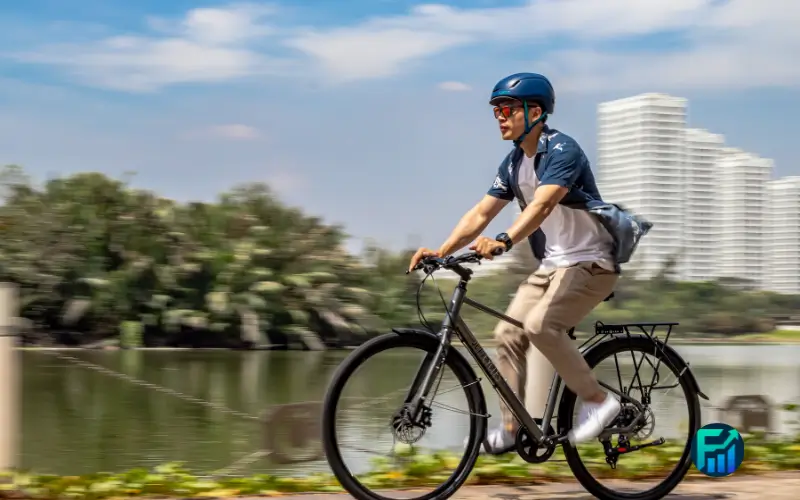
Buying a used bike is one of the simplest ways to cut your monthly costs and still get around your city. A transit pass, a few rideshare trips, and the odd taxi add up fast. For newcomers and anyone on a tight budget, that money matters. A reliable second-hand bike can replace a big chunk of those trips for a single cost up front. This guide covers everything about buying a used bike safely, from spotting a fair deal to avoiding scams and stolen bikes. Read on before you message a single seller.
A used bike can ease the pressure on your monthly budget
Think of a bike as a tool that pays you back every week. A monthly transit pass in most Canadian cities costs real money, and rideshare trips cost more. When you replace even half of those trips with a bike, the savings show up right away. Buying a used bike is what makes that switch affordable in the first place.
The money case for buying a used bike is simple. You spend once, then keep the savings rolling for months. A decent second-hand bike often costs less than two or three monthly passes. After that, your main costs are a lock, the odd tune-up, and your own effort.
The seasons work in your favour here. In the warm months you might ride most days and barely touch transit. The money you would have spent on passes or rideshares can go straight into a small savings buffer. By the time the snow arrives, that buffer helps cover a winter transit pass or the odd cold-weather cab.
That steady saving is the real return on buying a used bike. It turns a recurring cost into a one-time one. None of this makes you rich. It simply frees up cash you can put toward rent, groceries, or a bill that is due. That bit of breathing room is what most riders notice first.
The safest way to shop protects both your money and your bike
Where you buy matters as much as what you buy. Some sources are built to help beginners, while others put the risk on you. Start with the friendlier options and treat the open marketplaces with more care.
Community bike shops, often called Bike Kitchens, are the best place to begin. These are non-profit spaces where volunteers fix bikes and teach people to do the same. Many sell refurbished second-hand bikes at fair prices, and staff can check the bike over with you. You leave knowing what you bought and how to keep it running. For a first-timer, buying a used bike this way takes most of the guesswork out of it.
Online marketplaces like Kijiji, Craigslist, and Facebook Marketplace have far more choice. They also carry more risk. Buying a used bike online can still be safe if you follow a few firm rules.
- Meet in a busy public place during daylight, ideally near a police station or a bank with cameras.
- Bring a friend if you can, and tell someone where you are going.
- Never send an e-Transfer or a deposit before you see the bike in person.
- Pay only after you have inspected the bike and agreed on a price.
- Walk away if the seller pressures you or refuses to meet in public.
- Trust your gut, because a deal that feels off usually is.
That rule about e-Transfer is the one scammers count on. An e-Transfer is an Interac payment sent by email, and once it lands it is almost impossible to reverse. No honest seller needs your money before you have met in person.
Buying a used bike comes down to a careful inspection
The inspection is where you protect your money. A bike can look fine and still hide costly problems. You do not need to be a mechanic, only patient and willing to look closely.
The inspection is the most important step when buying a used bike. Work through the bike part by part and do not rush. If the seller will not give you a few minutes to check it over, treat that as a warning.
- Frame: check for cracks, dents, or heavy rust near the joints, since this is the one part you cannot cheaply fix.
- Tires: look for cracks, bald tread, or bulges, and factor in the cost if they need replacing.
- Wheels: spin each one and watch for wobble, since a small wobble is fine but a large one is not.
- Brakes: press each lever while rolling the bike, and feel that the pads grip firmly.
- Drivetrain: shift through the gears and listen for skipping or grinding, which points to worn parts.
- Serial number: find it and write it down, because your next step depends on it.
The drivetrain is the chain and gears that move the bike, and worn parts there can cost more than the bike itself. That last item on the list is the one people forget. Every bike has a serial number, usually stamped under the frame where the pedals meet.
Once you have the number, you can check whether the bike was reported stolen. The Canadian Police Information Centre, known as CPIC, runs a free public search on its website at cpic-cipc.ca. You can also check the number in the 529 Garage app, a free bike registry used by police across Canada. If either one flags the bike, walk away and tell the seller why.
This step protects you twice. You avoid handing your money to a thief, and you avoid riding a bike that police could seize later. Checking the serial number is a normal part of buying a used bike, and any honest seller will wait the two minutes it takes.
A good lock protects the money you just saved
Buying the bike is only half the job. A cheap lock can undo all your savings in seconds. Plan to spend part of your budget on protection from the start.
All the effort of buying a used bike is wasted if it gets stolen in the first week. A fair rule is to set aside about 10 to 20 percent of what you paid for the bike toward a solid lock. If you spent 200 dollars on the bike, a 20 to 40 dollar lock is reasonable. It feels like a lot up front, yet it costs far less than replacing a stolen bike.
Choose a U-lock, the rigid metal kind shaped like a U. Thieves cut through cheap cable locks in seconds with simple hand tools. A hardened U-lock forces them to work harder and longer, and most will give up and look for an easier target. Lock the frame and a wheel to something fixed and solid.
The lock is the cheapest insurance you will buy after buying a used bike. Skimping here is the most common mistake new riders make.
Bike share fills the gap when owning is not practical
Owning a bike is not the right fit for everyone. If you live in a small apartment with no safe storage, or in an area where theft is common, a bike of your own can become a headache. In that case, buying a used bike may not be your best first move. Public bike share can be a smart backup.
Bike share lets you unlock a bike from a public station, ride it, and return it to another station. You pay by the trip or by a membership, and you never worry about storage or theft. For short trips across town, it can cost less than a bus transfer.
Many people miss this part. Some Canadian cities offer reduced fares for low-income riders. In Toronto, residents of subsidized housing can get an annual bike share membership for a few dollars instead of the usual price. Other cities run their own discount programs, so check your local system before you assume it is out of reach.
Bike share and owning are not an either-or choice. For many people, buying a used bike still wins on cost over a full year, while bike share covers the days when riding your own does not make sense.
You do not need much to get started. A careful eye, a serial number check, and a good lock cover most of the risk in buying a used bike. Take your time, meet in public, and never pay before you inspect. The savings will follow, month after month, along with the freedom of getting around on your own terms. Your first ride is closer than you think, so start your search today.
Educational information, not financial advice.