Destiny Mastercard: credit after bankruptcy, but at a high cost
What you get, what you pay and how it compares
The Destiny Mastercard® is an unsecured credit card for people with less-than-perfect credit, including those with a past bankruptcy. It’s issued by The Bank of Missouri and serviced by Concora Credit. You don’t need a security deposit, and your payments are reported to all three major credit bureaus.
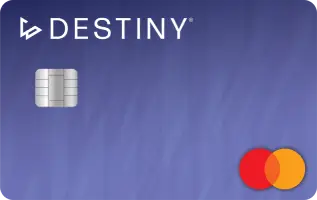
What you’ll pay depends heavily on the offer you receive, and the most common offer is expensive. Below, we explain what the card includes, how its offers differ, what to check before accepting and how it compares with its sibling cards.
What the Destiny Mastercard® includes
The card works like a regular Mastercard in the U.S., in stores, in apps and online. Destiny reports your payments monthly to all three major credit bureaus, so paying on time can help you build a positive payment history, while late payments can hurt it.
It also comes with Mastercard ID Theft Protection™, which monitors personal information such as your Social Security number and email addresses, and Zero Liability protection, so you’re not held responsible for unauthorized charges. The card doesn’t offer rewards, a welcome bonus or an intro APR.
If your application isn’t approved, no hard inquiry appears on your credit report, so your score isn’t affected.
What it costs: the offers vary
Destiny doesn’t publish its fees on its website, and reviews in 2026 describe more than one fee structure:
- The most widely marketed offer charges a $175 annual fee in the first year and $49 after that, plus a $12.50 monthly fee starting in the second year. That’s $175 in year one and about $199 a year after that.
- Other offers carry a $0 annual fee with a smaller monthly fee instead.
Across offers, reviews report a 35.9% APR, a 1% foreign transaction fee and a typical starting credit limit of around $700. Some cardholders report that the limit doesn’t increase over time.
Any annual fee is charged to the card when the account opens. On a $700 limit with a $175 fee, you start with about $525 available and a $175 balance before your first purchase.
Terms checked in September 2026. Destiny doesn’t publish its fees and APR on its public website, so review the full terms shown during the application before you accept the card.
Pros of the Destiny Mastercard®
- No security deposit required
- Reports to all three major credit bureaus
- Available to applicants with bad credit, including past bankruptcy
- No hard inquiry on your credit report if you’re not approved
Cons of the Destiny Mastercard®
- High annual fee on the most common offer
- Monthly fee starting in the second year on many offers
- 35.9% APR
- Low credit limit and no rewards
Destiny, Milestone and Indigo: sibling cards
Concora Credit services three cards for people with bad credit: Destiny, the Milestone® Mastercard® and the Indigo® Mastercard®. Destiny and Milestone are both issued by The Bank of Missouri, and their fee structures and terms are nearly identical. Choosing between them is less about the brand and more about the specific offer you’re shown.
If you’re considering more than one, compare the exact annual fee, monthly fee and credit limit in each prequalified offer. Opening more than one of these cards multiplies the fees without adding much benefit.
About The Bank of Missouri and Concora Credit
The Bank of Missouri has issued the Destiny Mastercard since April 2025. Before that, the card was issued by First Electronic Bank, so older reviews may still mention that bank. Concora Credit, based in Beaverton, Oregon, services the account and handles customer service, payments and account management.
Managing your account
After you’re approved and receive the card, you can create a login on Destiny’s online account site to check your balance, view statements and pay your bill.
Our take on the Destiny Mastercard®
The Destiny Mastercard can give people with seriously damaged credit, including a recent bankruptcy, access to an unsecured card that reports to all three bureaus. For some applicants, that access is the main reason to consider it.
On the most common offer, though, you’ll pay close to $200 a year to keep a card with a limit of around $700, and the credit bureaus don’t care whether your card was secured or unsecured. If you can afford a deposit, a secured card with no annual fee builds credit the same way at a fraction of the cost, and you get the deposit back.
If Destiny is your only option, look closely at your offer, pay in full every month and plan to move to a cheaper card once your credit improves. Approval isn’t guaranteed.
In the next article, we walk through how to apply for the Destiny Mastercard®.
*You will remain on this site*
Editorial Notice: All content published on this website is completely independent and aims to provide clear, useful, and up-to-date information about personal finance. We have no ties to banks, financial institutions or credit card companies. We are not affiliates and do not receive commissions or payments to promote products or services. Our website is monetized exclusively through the advertisements displayed on our pages. This content is for informational purposes only and is not financial advice.